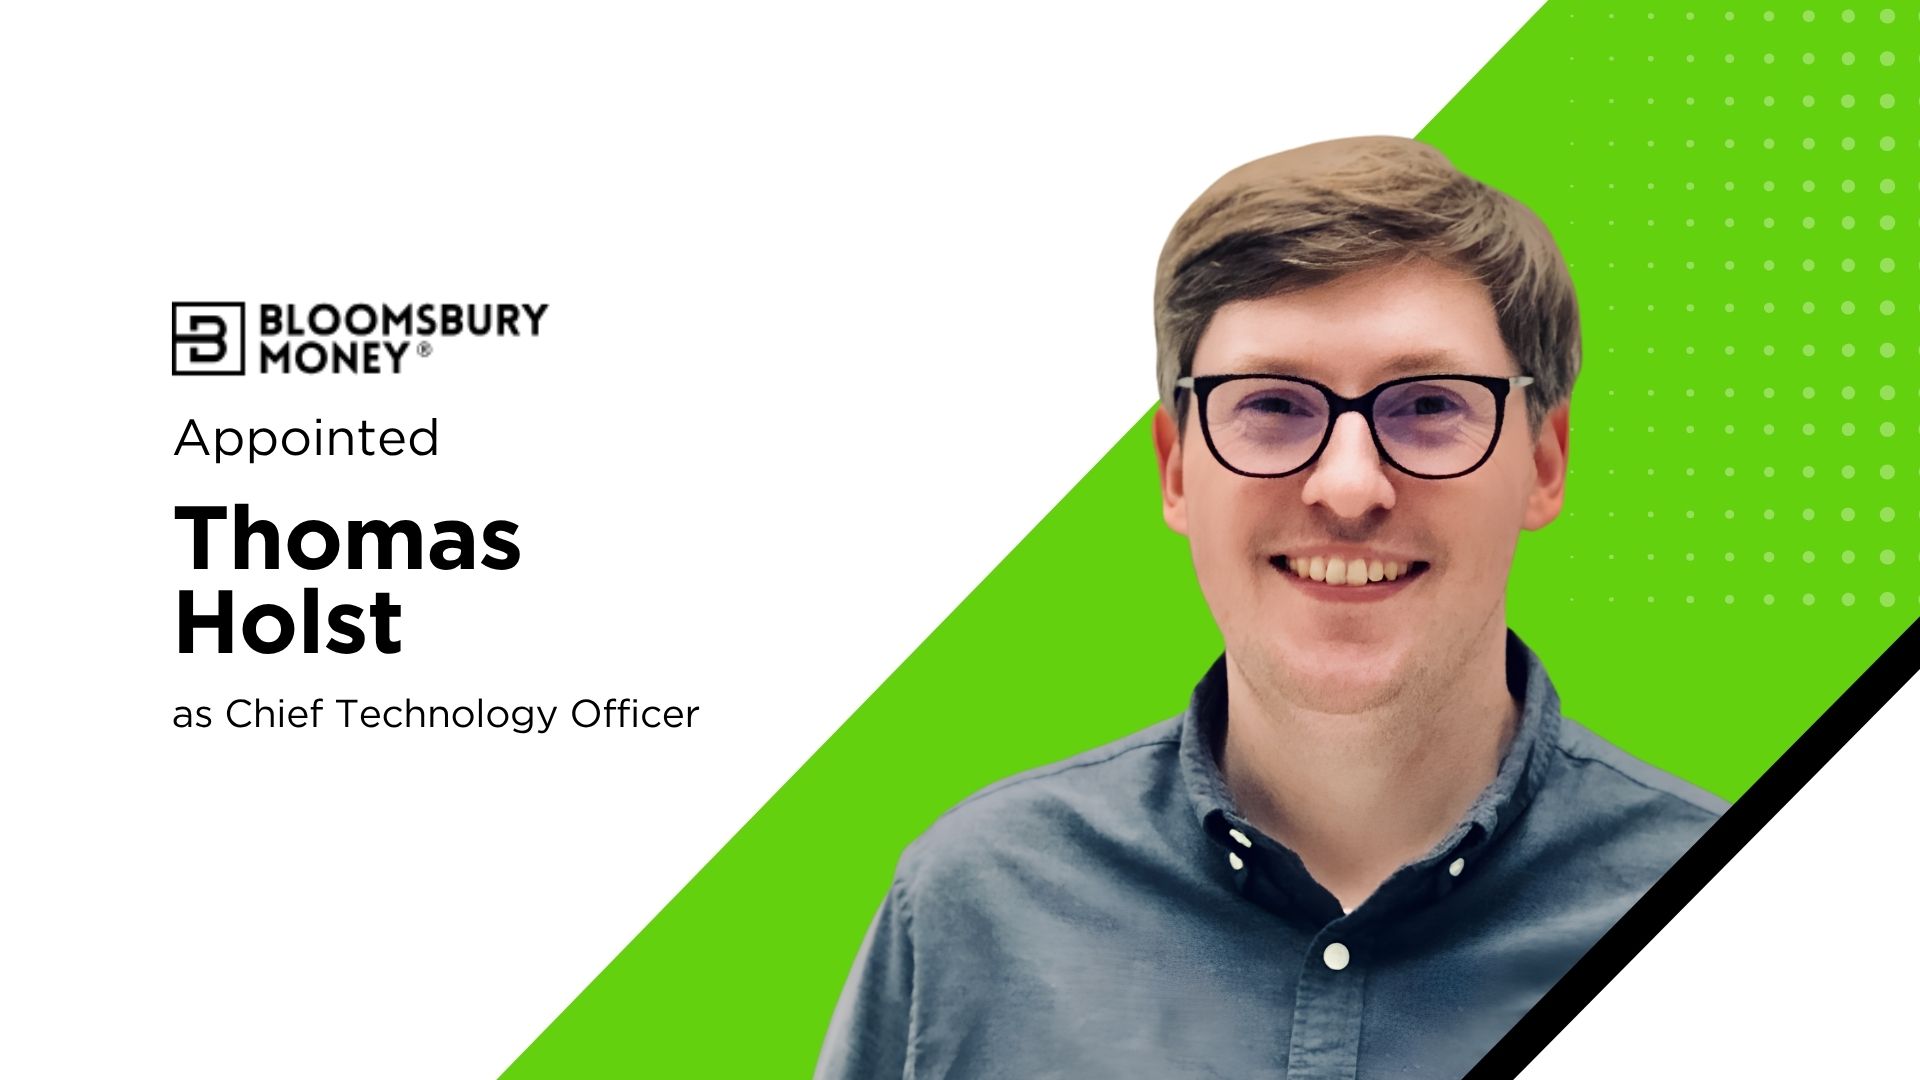
Bloomsbury Money Group has appointed Thomas Holst as Chief Technology Officer as the Jersey- and London-based financial services company prepares to expand its banking platform across additional jurisdictions and connect fiat, digital assets and local payment rails through a common technology architecture.
Bloomsbury Money makes technology central to expansion
Bloomsbury Money Group is strengthening its technology leadership as it moves from a regulated money services and virtual asset business toward what it describes as a multi-jurisdiction financial network.
The company has appointed Thomas Holst as Chief Technology Officer, giving him responsibility for technology strategy, engineering and platform architecture as Bloomsbury Money expands its financial services infrastructure.
Holst joins from SAP’s health technology ecosystem and brings more than a decade of experience working on data-intensive and privacy-sensitive technology platforms. Bloomsbury Money says his previous work included software and cloud infrastructure serving hospitals, researchers and health-data applications.
The appointment comes as the company seeks to bring its existing services—including multi-currency accounts, foreign exchange, cross-border payments and regulated virtual asset custody and transfers—onto a broader platform architecture.
The company’s ambition is to support several regulatory environments while maintaining a consistent technology and control framework.
Building one infrastructure layer for multiple forms of money
Bloomsbury Money’s longer-term proposition is built around interoperability between different forms of value and payment infrastructure.
The company says its planned network will allow fiat currencies, regulated digital assets and local payment rails to operate alongside one another. A transaction could therefore be routed through a bank transfer, card payment, domestic instant-payment network or digital-asset transfer depending on the requirements of the transaction and the applicable compliance controls.
That approach puts Digital Payments Platforms, Blockchain Financial Technology and traditional banking infrastructure into the same architecture.
The practical challenge is significant. Each payment rail can have different settlement processes, operating requirements and regulatory obligations. Digital assets introduce additional requirements around custody, transaction monitoring and asset-specific controls.
Rather than treating each capability as a separate product, Bloomsbury Money says it wants the underlying platform to provide a common technology and control layer.
Holst’s appointment is therefore more than a conventional technology leadership change. It is tied directly to the company’s attempt to build infrastructure that can operate across multiple currencies, asset classes, payment systems and regulatory jurisdictions.
Cross-border payments remain an interoperability problem
The strategy comes as financial institutions and fintech companies continue to address structural friction in cross-border payments.
A March 2026 paper from the Bank for International Settlements said cross-border payments remain more costly, slower, less accessible and less transparent than domestic payments. It identified limited interoperability and institutional differences between countries as important constraints, alongside the need for greater harmonisation of standards and more effective compliance regimes.
Those challenges are directly relevant to Bloomsbury Money’s proposed model.
A genuinely multi-rail payment network needs more than connectivity. It needs a mechanism for deciding which rail to use, verifying that the transaction satisfies applicable rules, managing liquidity and foreign exchange, and maintaining a reliable audit trail.
That makes technology architecture and regulatory controls closely connected.
Bloomsbury Money co-founder Manu Choudhary said the company wants to create infrastructure that behaves consistently across markets, while CEO Chris Park described resilience, auditability and regulatory traceability as core requirements for the platform.
Tokenised finance is adding another infrastructure layer
The company’s plans also arrive as financial institutions explore how tokenisation can work alongside existing payment infrastructure.
In May 2026, the BIS said Project Agorá had demonstrated the potential for tokenised central bank reserves and tokenised commercial bank deposits to support atomic settlement of wholesale cross-border transactions across currencies and jurisdictions. The project involves the BIS Innovation Hub, the Institute of International Finance, central banks and more than 40 regulated financial institutions.
The development does not mean digital assets are replacing conventional payment rails. Instead, it illustrates the direction of financial infrastructure research: different forms of tokenised money and existing payment systems may need to interoperate.
The BIS has also highlighted interoperability and common technical standards as important requirements for tokenised financial systems.
Bloomsbury Money is pursuing a commercial version of a related infrastructure concept by seeking to connect fiat and regulated digital-asset capabilities with local payment networks.
The distinction is important. The company has described a strategic direction and expansion plan, rather than announcing that a global multi-rail network is already operating at full scale.
Technology controls become part of the financial product
For a platform spanning multiple jurisdictions, the technology challenge extends beyond transaction processing.
Data protection, access controls, auditability, transaction monitoring, resilience and regulatory reporting all need to operate consistently while accommodating local requirements.
That is where Holst’s healthcare technology background becomes relevant to Bloomsbury Money’s stated strategy.
Healthcare systems operate under strict requirements around sensitive data, privacy and traceability. The company says it wants to bring the same engineering discipline to financial infrastructure.
In practical terms, that means treating trust as an architectural characteristic rather than an additional layer added after a product has been built.
For Open Banking Infrastructure and Banking Technology Innovation, this is increasingly important as financial services become more modular. A platform may depend simultaneously on banks, payment networks, APIs, cloud infrastructure, digital-asset custody systems and third-party service providers.
Expansion will test the model
Bloomsbury Money says it will initially build from its existing presence in Jersey and the Channel Islands before extending its regulatory footprint and payment-rail connectivity into additional markets.
The company has not disclosed a detailed timetable for each new jurisdiction or provided transaction-volume targets for the planned network.
That leaves execution as the next major test.
Connecting multiple forms of money is technically possible, but making the experience consistent across regulatory environments requires more than a common API. Payment routing, liquidity, compliance, settlement finality and operational resilience all have to work together.
For the wider Fintech Startup Ecosystem, Bloomsbury Money’s approach reflects a broader shift from single-purpose fintech applications toward financial infrastructure designed to connect multiple services.
Its new CTO will be responsible for turning that architecture into a production platform as the company expands.
If successful, the model could position the business at the intersection of Financial Technology, Digital Payments, Digital Assets and Banking Technology Innovation—with the common infrastructure layer becoming as important as the individual financial products delivered through it.
Market Landscape
Cross-border payments remain fragmented because domestic payment systems, regulatory frameworks and technical standards differ across jurisdictions. The BIS identified limited interoperability as one of the main constraints preventing cross-border payments from matching the efficiency of domestic systems.
At the same time, tokenisation is introducing new approaches to settlement. Project Agorá has demonstrated how tokenised central bank reserves and commercial bank deposits could support multi-currency wholesale settlement while retaining central-bank-money settlement characteristics.
For fintech providers, the emerging opportunity is increasingly about connecting payment rails rather than replacing every existing rail.
Top Insights
- Thomas Holst will lead Bloomsbury Money’s technology strategy as the company expands its banking platform into additional jurisdictions.
- The company wants to connect fiat, regulated digital assets and local payment rails through a common technology and control architecture.
- Cross-border payment interoperability remains a major industry challenge, with the BIS identifying fragmented systems and standards as important constraints.
- Tokenisation is creating new possibilities for cross-border settlement, but interoperability, regulatory controls and financial integrity remain central requirements.
- Bloomsbury Money’s expansion plan remains company-stated; specific launch dates, transaction targets and new jurisdictions have not been disclosed.
Get in touch with our fintech expert