A company needs to make payments to its foreign suppliers at the end of the week. Payments are made by the finances via the bank; however, those payments must go through various banks before reaching the supplier’s account.
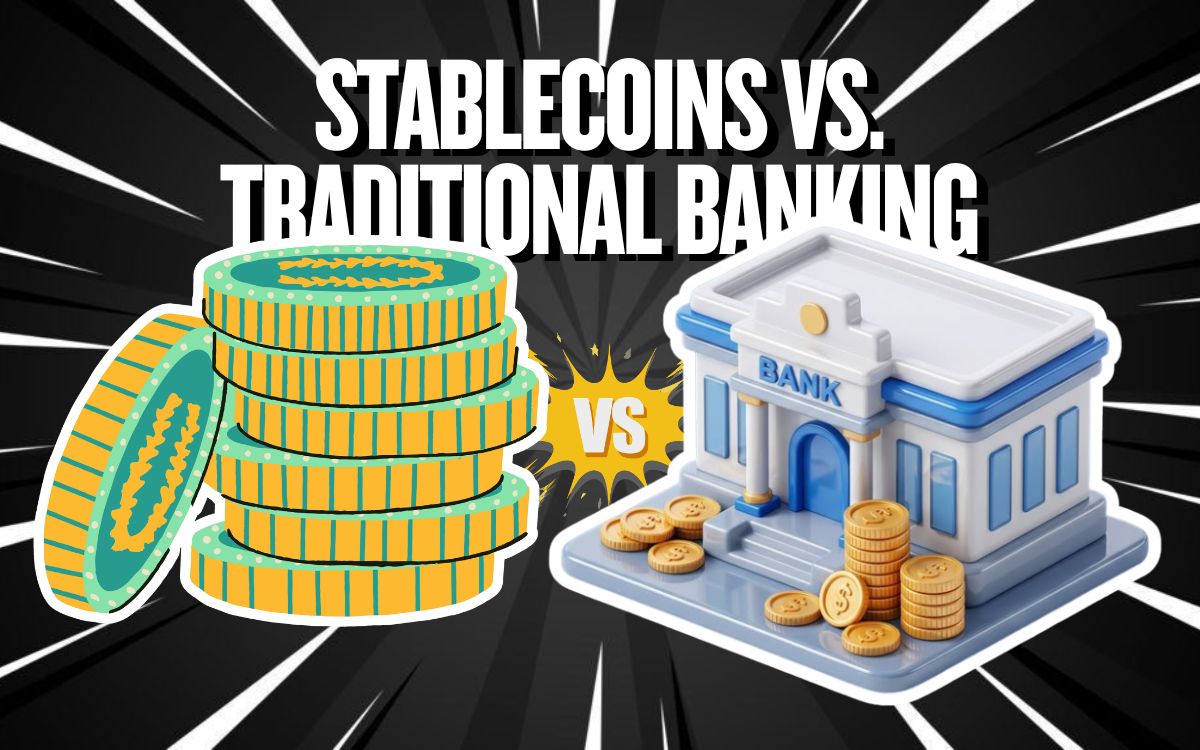
A stablecoin-based payment could follow a different path, allowing the same value to move across blockchain infrastructure with settlement designed for real-time transactions. The question is no longer whether stable coins can coexist with banks. It is which parts of the traditional payment model will change and where the two systems will converge.
This article discusses the future of digital payments.
Why the Collision Between Stablecoins and Traditional Banking Was Inevitable
For decades, traditional banks have controlled the infrastructure through which businesses move money. These systems provide trust and oversight, but they were not designed for an economy that operates digital transactions.
Stablecoins are combining the stability of currencies with blockchain settlement, so that payments can move without relying on the traditional payment chain. That does not make banks irrelevant. Banks still provide liquidity, credit, custody, compliance, and access to the broader financial system.
Stablecoins challenge the assumption that every payment must move through conventional banking rails. As adoption expands, financial institutions are being pushed to determine where blockchain settlement fits into their existing infrastructure.
What Stablecoins Offer That Traditional Banking Cannot
1. Faster Cross-Border Payments
Stablecoins can move value directly between digital wallets, reducing the number of intermediaries involved in settlement.
A software company paying contractors across multiple countries could settle payments in stablecoins without routing every transaction through a correspondent banking chain.
2. Transaction Visibility
Blockchain transactions create a shared record that participants can verify. This can improve visibility into payment status compared with systems where information is distributed across several financial institutions.
A multinational company managing thousands of supplier payments could use blockchain records to track when funds were transferred and settled.
3. Access to Digital Dollar Liquidity
Stablecoins can help dollar-denominate digital value without requiring every participant to maintain a conventional dollar banking relationship.
A business operating in a market with limited access to international banking infrastructure could use a dollar-backed stablecoin for certain cross-border transactions.
How Traditional Banks Are Responding to Stablecoins
1. Building Stablecoin Payment Infrastructure
Banks are investing in the technology required to issue, hold, transfer, and settle stable costs. This allows them to participate in blockchain payments without abandoning their existing infrastructure.
A bank could integrate stablecoin wallets into its corporate banking platform, allowing treasury teams to manage traditional deposits and digital assets through a single interface.
2. Expanding Digital Asset Services
Banks are positioning themselves as trusted custodians for digital assets. This extends an existing capability to safeguard financial assets into the stablecoin ecosystem.
A corporate treasury could hold stable coins with a regulated bank rather than managing private keys and digital wallets.
3. Connecting Stablecoins with Existing Payment Rails
Stablecoins can handle the digital settlement layer while banks continue providing conversion, compliance, and account services.
A business could send a stablecoin payment to an international supplier, while the supplier receives fiat currency in its conventional bank account through the bank’s settlement infrastructure.
Consumer Trust as the Decisive Variable
Technology can change how payments move, but trust determines whether consumers are willing to use it. This is important for stable coins in payments, where adoption depends on confidence and ability to convert digital assets into currency when required.
A payment system may offer faster settlement, but that advantage has limited value if users question whether the digital asset will maintain its value or whether their funds can be recovered when something goes wrong.
Trust will also determine how stablecoins fit into the digital payment’s future. If financial institutions can provide governance, reliable conversion between currency and stablecoins, transaction controls and disclosures, stablecoins can become another layer of mainstream payment infrastructure.
Which Model Will Actually Shape the Future of Payments
The deciding factor will be trust backed by measurable business value. The future will be shaped by systems that can deliver speed without compromising the controls expected from financial institutions. The most likely outcome is convergence. Stablecoins can provide a new settlement layer, while banks provide the regulated infrastructure, liquidity and financial services around it.
Paramita Patra is a content writer and strategist with over five years of experience in crafting articles, social media, and thought leadership content. Before content, she spent five years across BFSI and marketing agencies, giving her a blend of industry knowledge and audience-centric storytelling.